How to File a Roof Insurance Claim in Fort Worth: A Step-by-Step Walkthrough
May 8, 2026 · 9 min read · By the LoneRidge Roofing Team
Filing a roof insurance claim in Fort Worth does not have to feel like a maze. After a Tarrant County storm, the homeowners who fare best are simply the most organized: they document before they call, understand each step before it happens, and keep every paper in one place. This walkthrough takes you from the first photos on the ground through the adjuster meeting, the Texas decision timelines, and the repair or replacement itself — plus what to do if the answer is not what you expected.
Step 1: Confirm Damage and Secure the Home
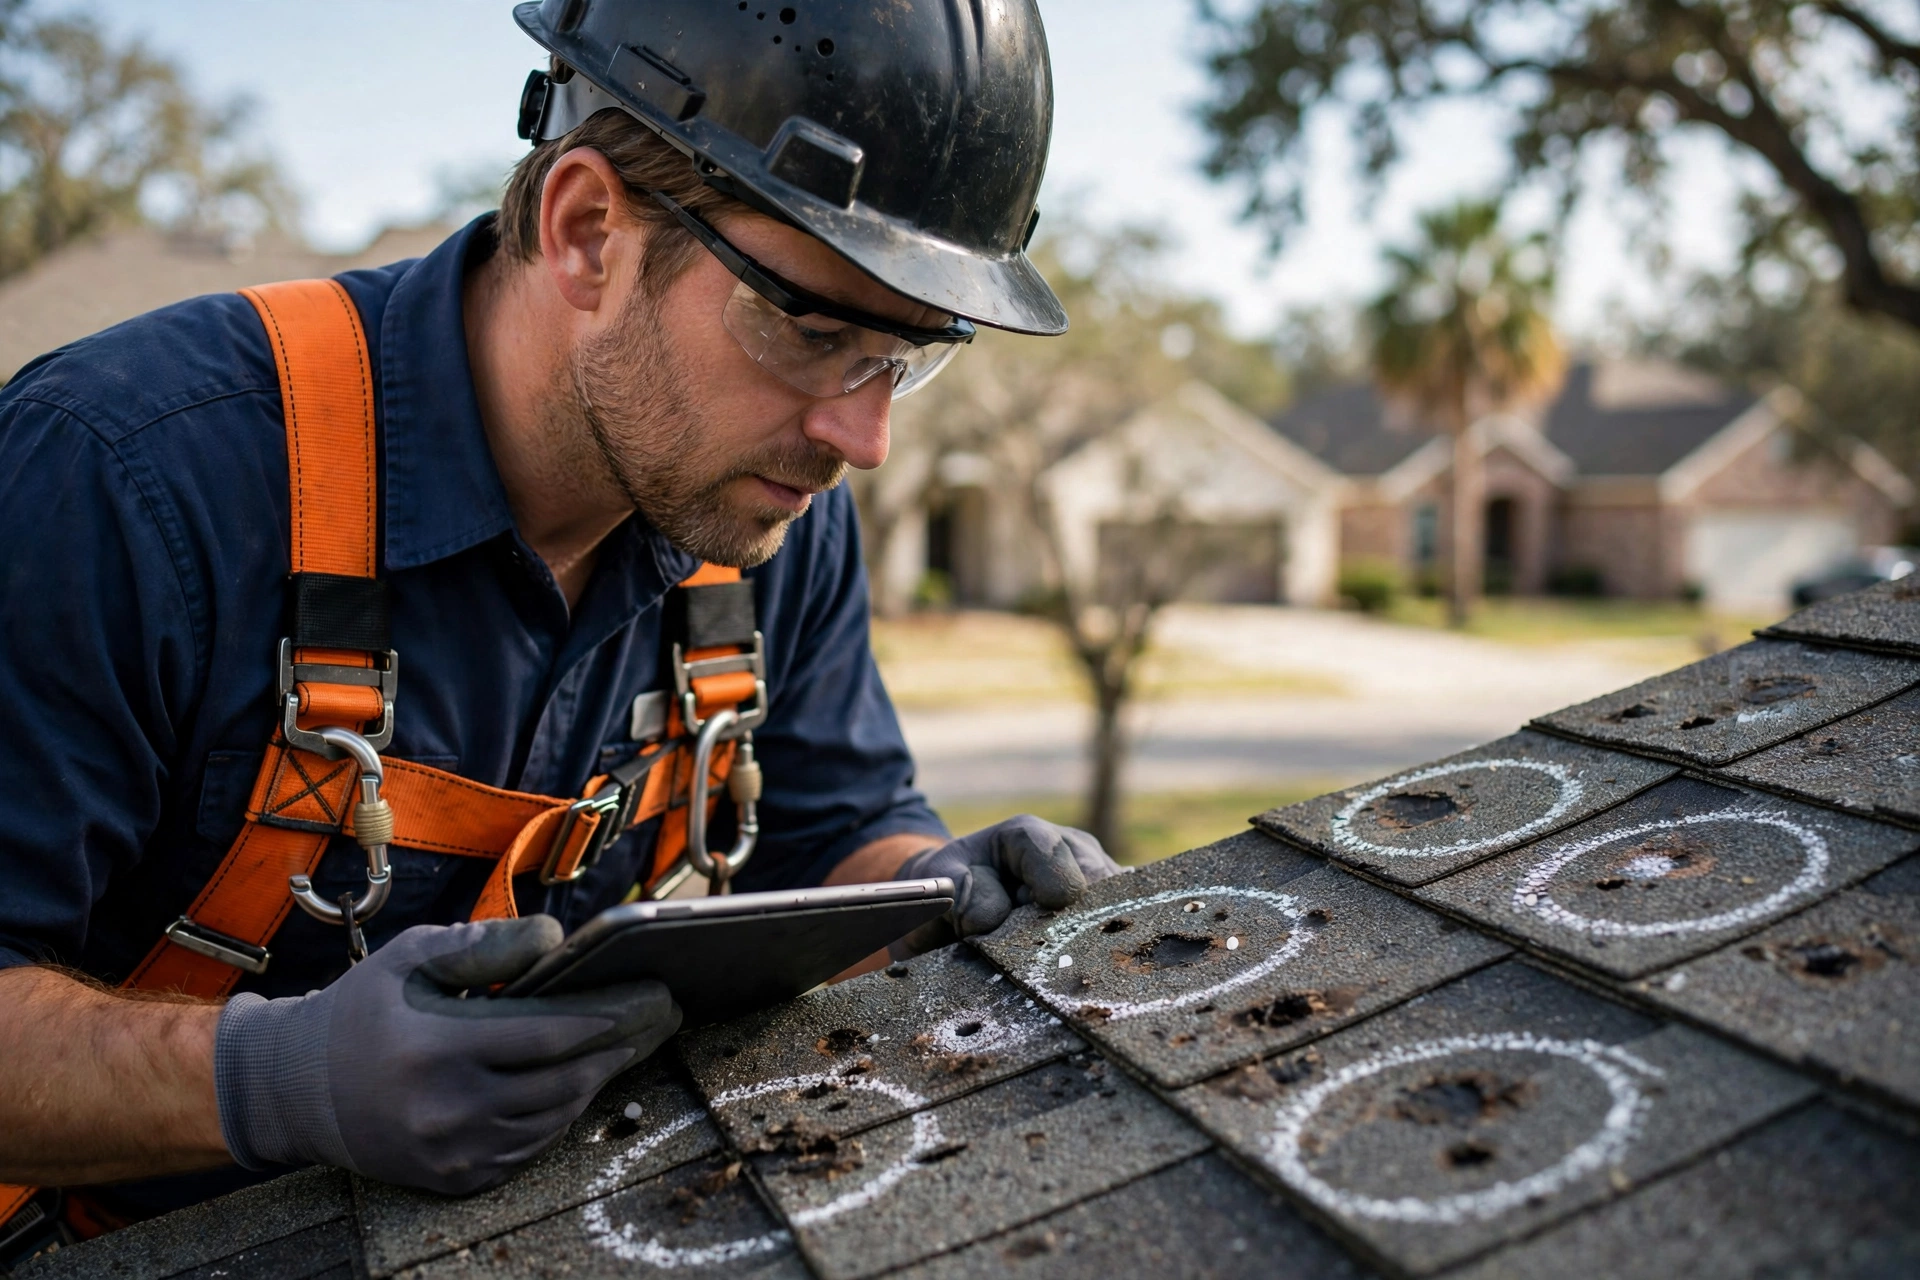
Before any claim, confirm there is something to claim. After a Fort Worth storm, check from the ground for missing shingles, dented gutters and vents, granules at downspouts, and interior stains. If the roof is actively leaking or a section is exposed, arrange temporary protection — a properly secured tarp or emergency repair — and keep every receipt. Insurers generally expect homeowners to prevent further damage, and documented emergency steps support that you did your part.
Get a professional inspection before filing if you can. A documented inspection with slope-by-slope photos tells you whether you are looking at functional storm damage worth claiming, minor damage better handled as a direct repair, or wear that insurance will not cover. Filing a claim for purely cosmetic or age-related issues wastes time; filing with solid evidence of storm damage starts the process on firm ground.
Step 2: Gather Your Documentation Checklist
Assemble your file before you call. You will want your policy number and declarations page, the exact storm date and any weather evidence for your Fort Worth address, dated photos of exterior and interior damage, your inspection report with photos, receipts for temporary repairs, and a list of any personal property damaged by leaks. Note your wind and hail deductible in dollars — in Texas it is often 1% or 2% of the home insured value — so the economics of filing are clear from the start.
Keep this file in one folder, physical or digital, and add to it as the claim proceeds. Every letter, email, scope sheet, and payment record goes in. Tarrant County homeowners dealing with large storm events may talk to several adjusters or representatives over a claim; your own complete file keeps the facts consistent no matter who is on the phone.
- ★Policy number and declarations page
- ★Storm date plus weather evidence for your address
- ★Dated photos of roof, metals, and interior damage
- ★Written inspection report with slope-by-slope photos
- ★Receipts for temporary repairs and damaged property list
Step 3: File the Claim and Track the Timelines
File through your insurer claims line, mobile app, or agent, and record the claim number, the date and time you filed, and the name of anyone you speak with. Briefly and factually describe the storm and the damage found — your documentation does the persuading. Ask what documentation the insurer needs from you and how to submit it, since submitting everything requested promptly starts important clocks.
Texas Insurance Code Chapter 542 provides the framework: the insurer must acknowledge your claim within 15 days after receiving it; once you have provided all required documentation the insurer requested, it must accept or deny within 15 business days; and if approved, it must pay within 5 business days after approval. Put those dates on a calendar from your actual submission dates, and follow up in writing if communications stall, referencing the claim number every time.
Step 4: Prepare for the Adjuster Meeting
The adjuster inspection is the centerpiece of the claim. Be present if at all possible, and have your contractor present as well if you have chosen one — a roofer can safely access the roof, point to documented damage, and discuss scope in technical terms while you handle the policy conversation. Share your inspection photos and report in advance or at the meeting, and walk the interior together to review any leak damage.
During the visit, take your own notes: which slopes the adjuster inspected, what damage they acknowledged, and what they said about next steps and timing. Ask how the scope and pricing will be delivered and how to submit additional information if something was missed. A respectful, evidence-based meeting serves everyone. If access was limited by weather or safety, ask how and when the remaining inspection will be completed rather than assuming it happened.
Step 5: Review the Decision and Scope Carefully
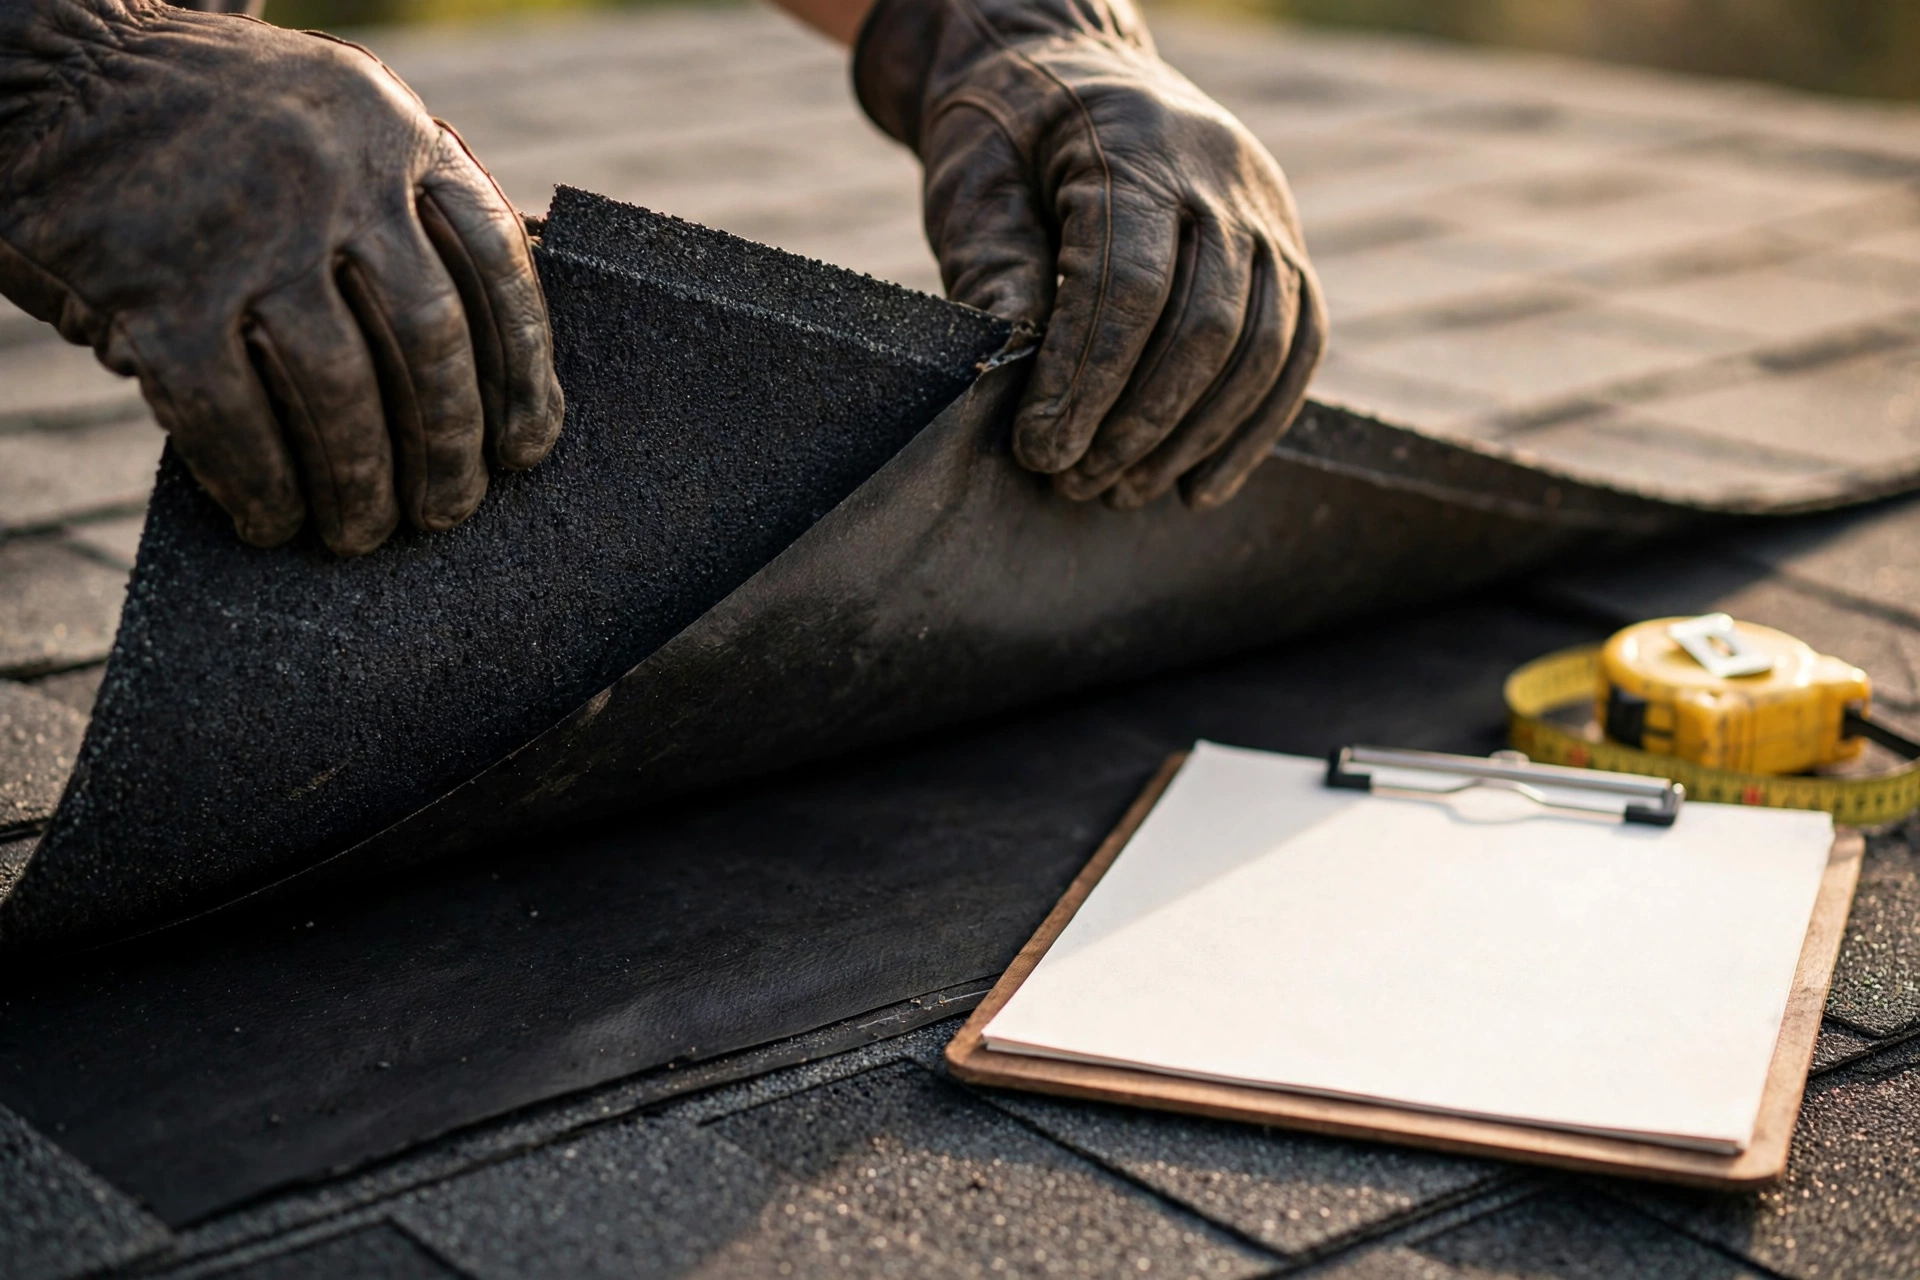
If the claim is approved, you will receive a scope of work and a payment structure. Many Texas policies pay actual cash value first, holding back depreciation until the work is complete and invoiced — confirm exactly how your recoverable depreciation is released. Compare the insurer scope line by line with your contractor scope: materials, quantities, flashing, ventilation, and code-required items. Differences are common and are usually resolved through a documented supplement process, not argument.
If the claim is denied or scoped far below the documented damage, read the decision letter closely for the stated reason. Sometimes the issue is a missing document or a disagreement about one slope; sometimes it is a coverage interpretation. You can submit additional evidence, request a re-inspection, and ask for explanations in writing. Keep everything factual and documented — persistence with evidence is legitimate and often effective.
Step 6: Complete the Work and Close the Claim
Choose your contractor on evidence, written scope, and materials — not on deductible promises. Remember that it is illegal in Texas for a contractor to waive, absorb, or rebate your insurance deductible, so plan to pay it as part of the job. Agree on a payment schedule tied to milestones, confirm material specifications in writing before installation, and photograph the work in progress, especially decking or flashing conditions uncovered during tear-off.
When the work is finished, submit the final invoice and completion documentation promptly so any held-back depreciation can be released under your policy terms. Keep the full claim file even after closing — warranties, material records, and claim documents all matter if you sell the home or face the next Fort Worth storm season. A well-documented roof history is an asset in its own right.
Not Sure What Your Roof Needs?
Get a photo-documented inspection and decide with evidence.
Questions, Answered
Yes, in most cases. A documented inspection confirms whether functional storm damage exists, gives you photo evidence for the claim, and helps you avoid filing for damage that is below your deductible or not covered, such as pure wear and aging.
Timelines vary with storm volume, but Texas law frames the process: acknowledgement within 15 days, a decision within 15 business days after all required documentation is received, and payment within 5 business days after approval. Your adjuster scheduling and documentation completeness affect the practical pace.
Read the decision letter for the specific reason, then respond with evidence: additional photos, your inspection report, or documentation of items missed. You can request a re-inspection and submit a documented supplement. Keep all communication written, factual, and tied to your claim number.